Public adjusting news
This Insurance Settlement Is Exactly Why You Need a Public Adjuster
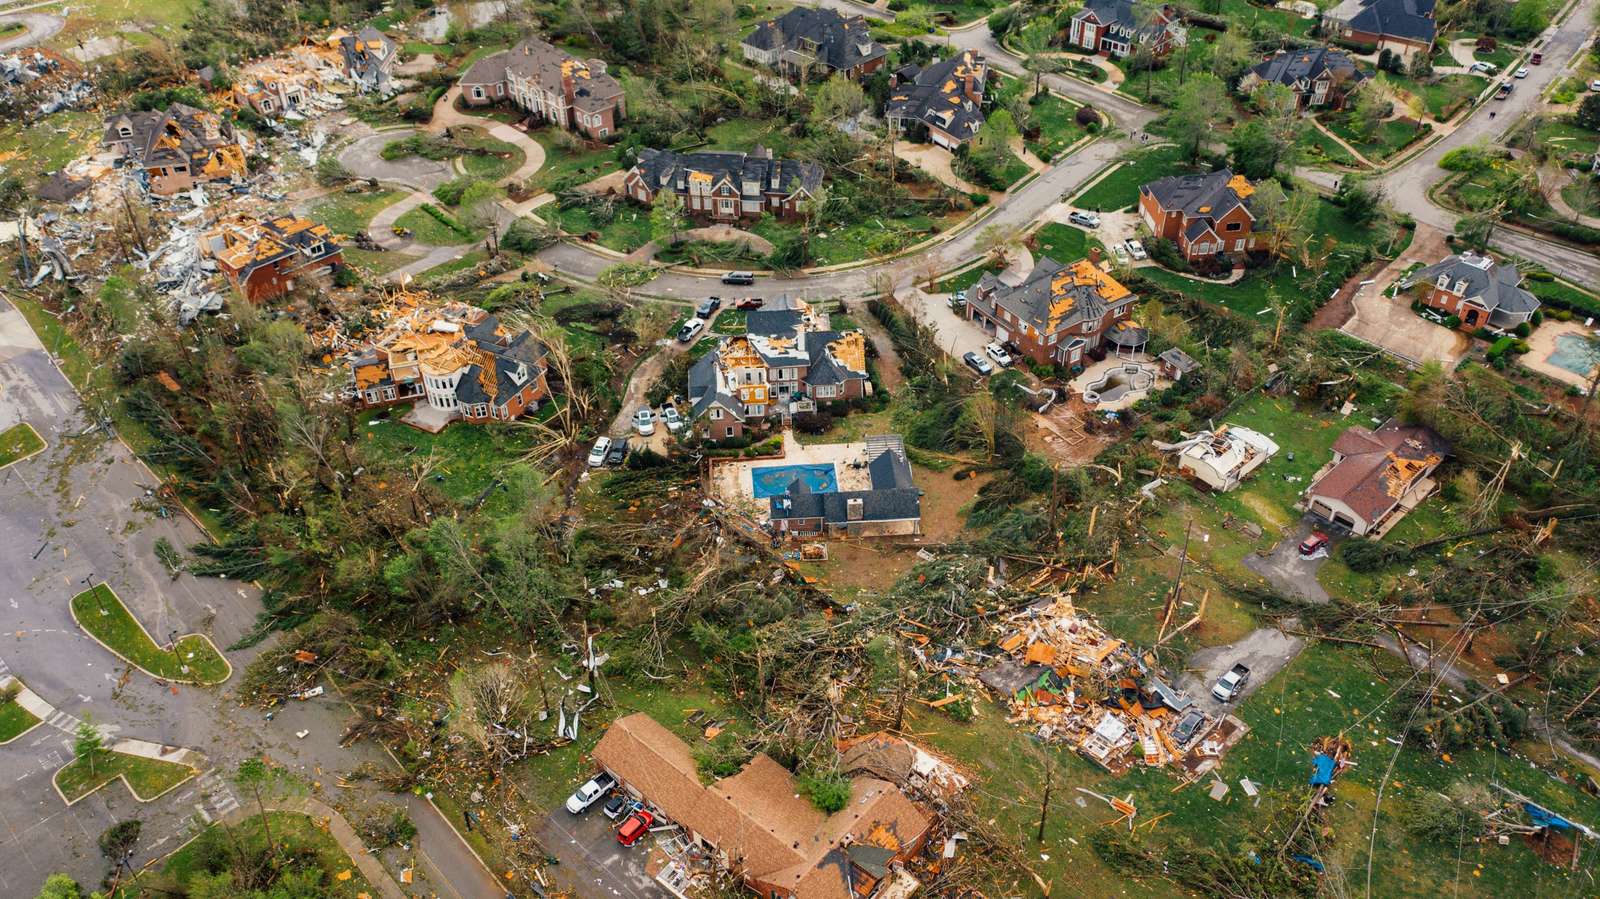
On November 13, 2026, the Oklahoma Insurance Department announced that State Farm Fire and Casualty Company agreed to a settlement of more than $45 million. The reason: a state examination found that State Farm “improperly denied or failed to pay for roof damage and necessary repairs” on Oklahoma homeowners’ wind and hail claims.
State Farm says it disagrees with the findings. But the lesson for every homeowner is the same. The company paying your claim is not the one looking out for you. That’s exactly why you should hire a licensed public adjuster.
What the settlement says
According to the Department, the settlement includes:
- At least $35 million to make affected homeowners whole
- $10 million for the Strengthen Oklahoma Homes grant program
- $2.86 million in fines and examination expenses
Eligible homeowners with a wind or hail claim dated January 1, 2021, through December 31, 2025, that was closed without payment, including partial payments and claims ruled under the deductible, get another chance. An independent third-party administrator will review those claims, and State Farm will mail notices explaining how to opt in.
Commissioner Glen Mulready said the Department “weren’t willing to simply take State Farm’s word” and sent independent engineers into the field to inspect roofs.
In a statement published by KOCO, State Farm said it evaluates each claim on the facts of the loss and the customer’s policy, has responded to more than 100,000 Oklahoma claims in the past five years, and that a limited review is not a complete picture of its practices.
Their adjuster vs. your adjuster
None of this means every roof claim was underpaid. It shows how much rides on how the damage is documented, how the policy is read, and who is speaking up for the homeowner.
- The insurance company’s adjuster is hired and paid by the insurer. They handle claims every day, for the company that writes the check.
- A public adjuster is licensed by the state to represent you, the policyholder. The job is to document the full loss, read the policy, build the claim and negotiate on your behalf.
Most families file a major claim once or twice in a lifetime. That’s not a conspiracy. It’s an imbalance, and a public adjuster exists to close it.
Fire claims raise the stakes
CMA handles more fire claims than any other kind of loss. A damaged roof is serious. A house fire is often the biggest financial event a family will ever face.
A fire claim can include the structure, smoke and soot, contents, additional living expenses, asbestos and other hazardous materials, and the code upgrades required to rebuild. Miss a category or misread the policy, and that money can stay on the table. (Our guide to fire contents claims covers the belongings side.)
Waiting years for a regulator to reopen a closed file is a poor substitute for getting the claim right the first time.
What to do after a loss
- Get everyone safe. Don’t enter an unsafe structure.
- Notify your insurer promptly, as your policy requires.
- Photograph the damage, rooms and contents before debris is removed.
- Prevent further damage when it’s safe, and keep your receipts.
- Don’t sign a final settlement, release or contractor agreement you don’t understand.
- Keep your policy, claim number, estimates and notes in one file.
- If a claim is denied or closed without payment, ask what was inspected and why.
- Talk with a licensed public adjuster early.
A note for Oklahoma homeowners
CMA is not licensed in Oklahoma and can’t handle Oklahoma claims. If you may be eligible for this review, watch for State Farm’s notice and follow the Oklahoma Insurance Department’s guidance at oid.ok.gov.
Get a free claim review
Claim Management Adjusters has worked for policyholders since 2009. We’re licensed in Indiana (firm license #3971901) and work fire, roof, wind and storm claims for homeowners in Indiana, Ohio, Kentucky, Tennessee, Maryland, North Carolina, South Carolina and Georgia. No ethical firm can promise a result, but we’ll tell you honestly whether we can help.
This article is general information, not legal advice or a guarantee of any claim result. It summarizes published reports about a settlement between the Oklahoma Insurance Department and State Farm, and State Farm disputes the Department’s findings. Outcomes depend on the facts, the policy and applicable law. Claim Management Adjusters is a licensed public adjusting firm, Indiana firm license #3971901, and is not licensed in Oklahoma.
Sources
- KOCO News, “State Farm agrees to over $45M settlement after investigation into Oklahoma roof damage claims,” Nov. 13, 2026: koco.com
- Oklahoma Insurance Department news release, Nov. 13, 2026: oid.ok.gov/111226
- Oklahoma Insurance Department, State Farm settlement information: oid.ok.gov/state-farm-settlement