From CMA
Know your rights before you settle
Plain answers on insurance claims, from public adjusters who work for you, not the insurance company.
Free homeowner tool
Contents Inventory Workbook
List what you lost after a fire, storm, or water loss, room by room. Free, private, and it runs in your browser, so nothing is sent to anyone.
Open the workbook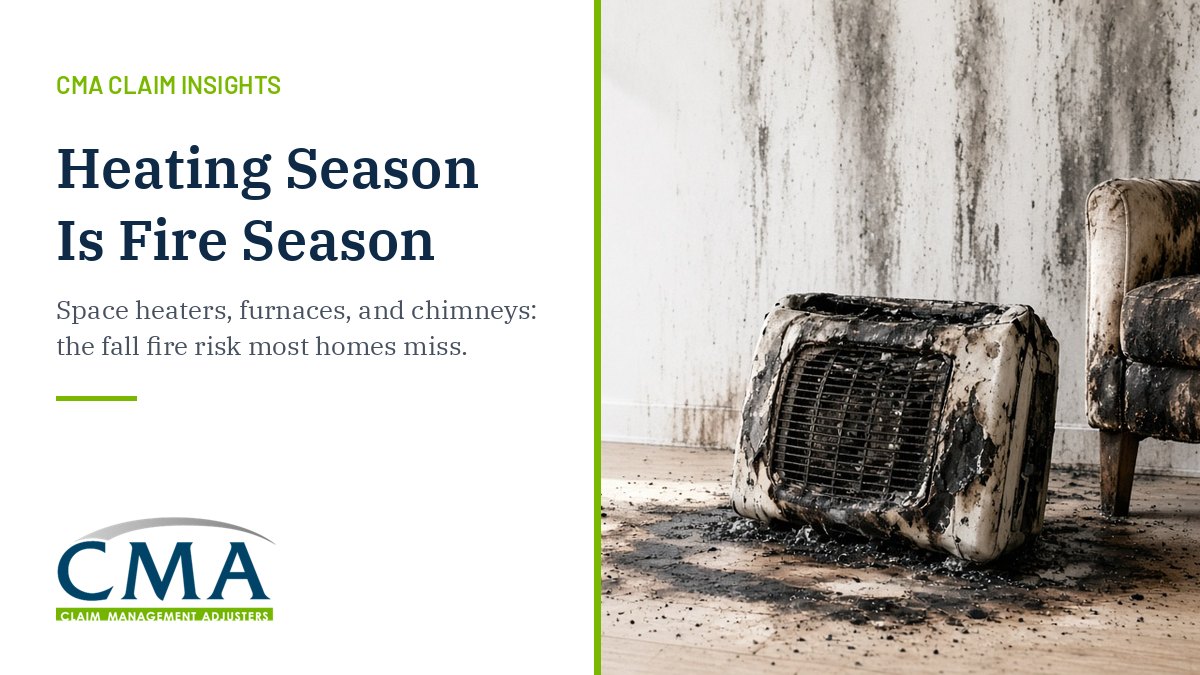
Fire claims
Space heaters and furnaces: the fall fire risk most homeowners miss
The first cold night of fall is when heating fires start. Where they begin, a short checklist, and why your own public adjuster matters if smoke spreads.
Read the guide
Fire claims
Thanksgiving is the top day for home cooking fires
More home cooking fires start on Thanksgiving than on any other day. How to keep your kitchen off that list, and what to do if a holiday fire hits your home.
Read the guide
The claim
Your insurance company’s adjuster vs. a public adjuster
The insurance company already has an adjuster on your claim. Here is who they work for, what a public adjuster does differently, and when to bring one in.
Read the guide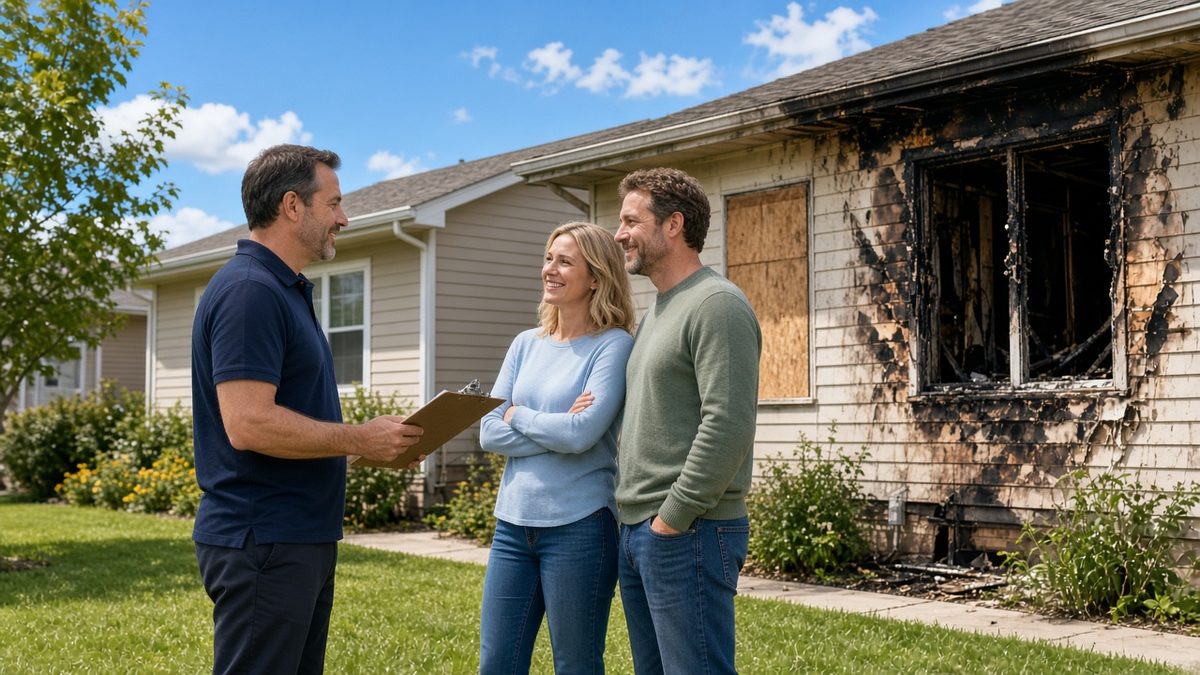
The claim
Why hire a public adjuster
The carrier already has an adjuster. A public adjuster is licensed to represent you — on the paperwork, the estimate, and the fight over the number.
Read the guide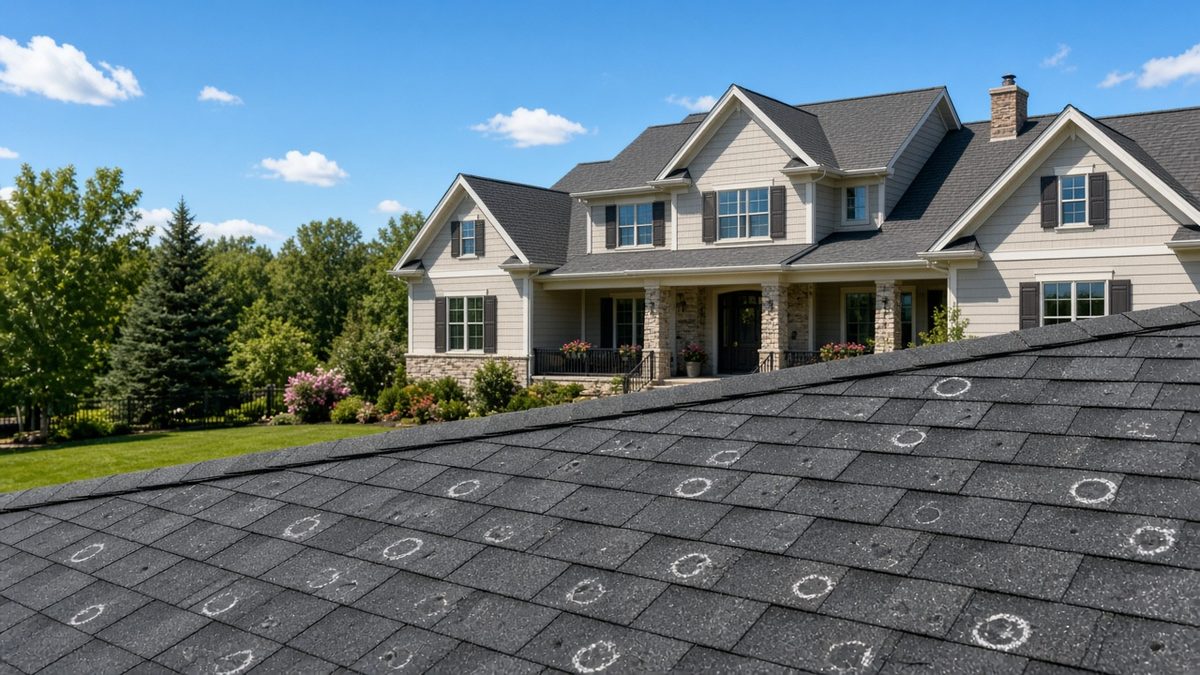
Storm claims
Wind and hail damage the carrier misses
Missing shingles are the easy part. Hail bruises, lifted flashing, and interior leaks show up later — after a low first offer is already on the table.
Read the guide
Appraisal & umpire
How insurance appraisal actually works
When the fight is the amount of loss — not whether it is covered — appraisal is often faster and cheaper than a lawsuit. Here is the process.
Read the guide
Fire claims
Smoke and soot are part of the fire claim
A room that burned is not the whole loss. Soot travels through HVAC and wall cavities. Wipe-downs do not restore a house that still smells like fire.
Read the guide