Fire & smoke
A room that burned is not the whole claim
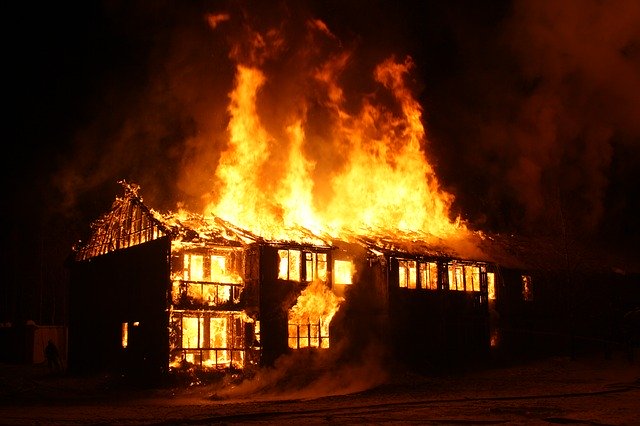
Fire, smoke, and soot travel. Carriers like to pay for what they can see from the driveway. CMA scopes the structure, the HVAC, the contents, and the time you cannot live in the house.
What we put in the file
- Structural burn, heat, and collapse — not a patch list.
- Smoke and soot in cavities, HVAC, and contents that still smell after a wipe-down.
- Contents inventories that actual families can finish, with depreciation handled correctly.
- Additional living expense when the policy provides it and the house is not livable.
- Code upgrades and matching when the ordinance or law endorsement applies.
How it works
Our 5-step process
Clear, documented, and run by people who do this every day. You should not have to become an insurance expert after a fire or a storm.
01
Free Claim Review
Send the loss details. We review the damage, the policy posture, and whether CMA can add value — at no cost and with no obligation.
02
Inspect & Scope
We inspect the property, photograph the loss, and read the policy line by line so coverage is not left on the table.
03
Document & Estimate
Professional documentation and an Xactimate estimate built the way carriers actually evaluate claims — not a napkin sketch.
04
File & Negotiate
We deal with the company adjuster, the desk examiner, and the delays. You are not the one arguing over depreciation and hidden damage.
05
Settlement
We stay on the file until the settlement reflects what the policy owes. If the number is still wrong, appraisal is on the table.
Do not let them decide alone
Get a professional review before you take their number
Call 844-262-9110 or send the form. No upfront fee. We only get paid when the claim pays.
Call 844-262-9110